Goldman Sachs has moved global equities to overweight on expected third-quarter earnings growth of 25%, but the S&P 500 closed just 0.09% below its high of the year.
📑 Contents
- 🧭 Before You Open the Terminal
- 📌 Key Market Indicators Dashboard
- 📊 Story in detail
- 🏢 1. Goldman goes overweight global equities on expected earnings growth of 25%, but the index has no cushion and the banks sit the first exam
- 🔭 Scenarios and invalidation
- 🚨 Strategic Alerts
- 📜 Disclaimer & Fantiborsa™ Maxim
Monday, October 12, 2026 — market data as of Friday’s close, October 9
🏛️ Pretore on the case:
long_attiva— stop 7799.4451 — AVWAP_C 7731.6329 (Δ+1.03% vs close) — snapshot 2026-10-12 · pipeline stockcharts_downloader v6.9.8
🧭 Before You Open the Terminal
🏢 Earnings and strategy: the upgrade buys a promise
Goldman Sachs has moved global equities to overweight on a three-month view, from neutral, because valuations have come down and earnings are holding up: consensus expects S&P 500 third-quarter earnings to grow 25%. Yet on Friday the index closed at 7,811.54, just 0.09% below its highest close of the year. If valuations came down, the index didn’t.
📉 Banks: the first exam goes to the sector moving the other way
JPMorgan, Goldman Sachs, Wells Fargo and Citigroup report tomorrow, Bank of America and Morgan Stanley on Wednesday. Over the past month the S&P 500 is up 2.3%; the big-bank ETF is down 9.1%. And Goldman’s upgrade lands the day before Goldman’s own results.
🏛️ Inflation and rates: Goldman’s barbell runs through Wednesday
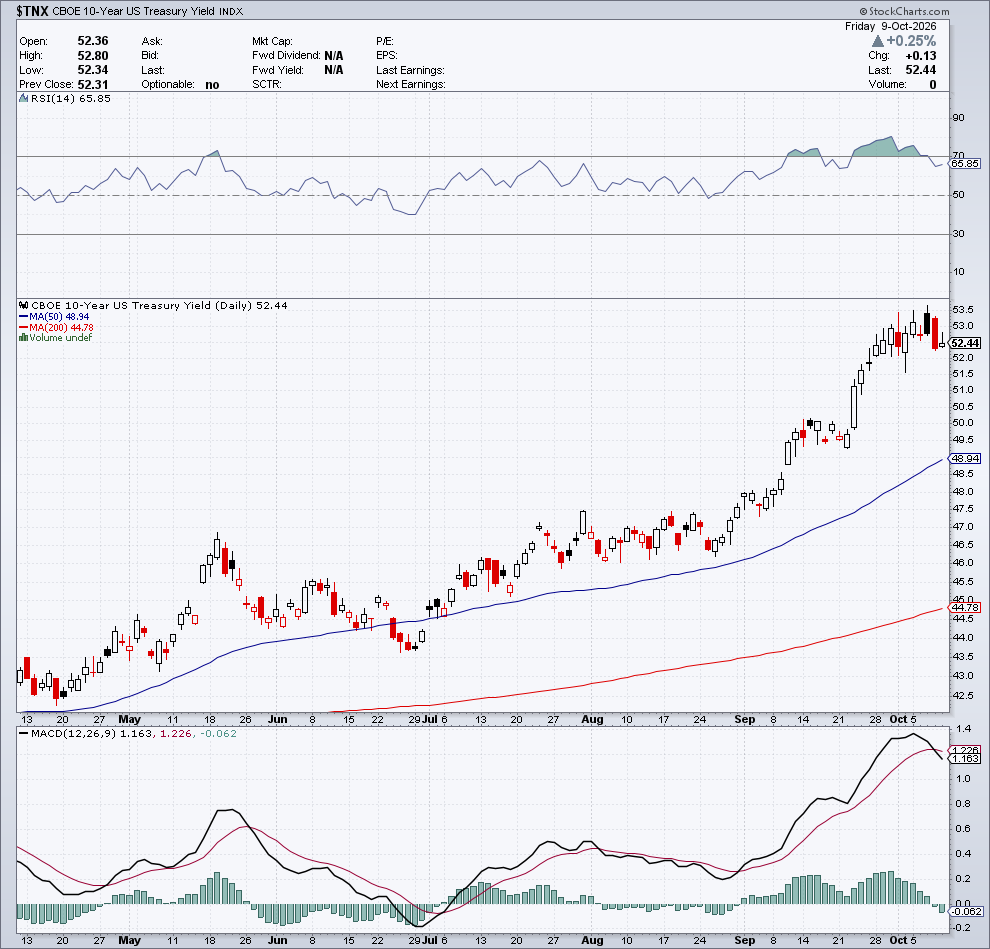
September CPI is out Wednesday at 2:30 p.m. Italian time, expected at 3.6%, up from 3.4%, according to the consensus reported by Yahoo Finance. One of the two legs of Goldman’s recommended strategy is rate-sensitive, bond-like stocks — and utilities, the worst sector of the month, are the textbook example. In practice, it’s a bet that yields stop rising, with the 10-year at 5.24%, up 41 basis points in a month.
Verdict
🔴 High priority — Fantiborsa’s take: Monday the upgrade, Tuesday the results of the bank that signed it, Wednesday the inflation print that could take it apart. The week has already set the reading order. Stop at chapter one and you’ve bought the cover and missed the plot.
Trust me: this one’s worth five minutes ☕
📌 Key Market Indicators Dashboard
Data as of the close on Friday, October 9, 2026. Table limited to the indicators touched by the story.
| Indicator | Value | Change | Reading | Signal |
|---|---|---|---|---|
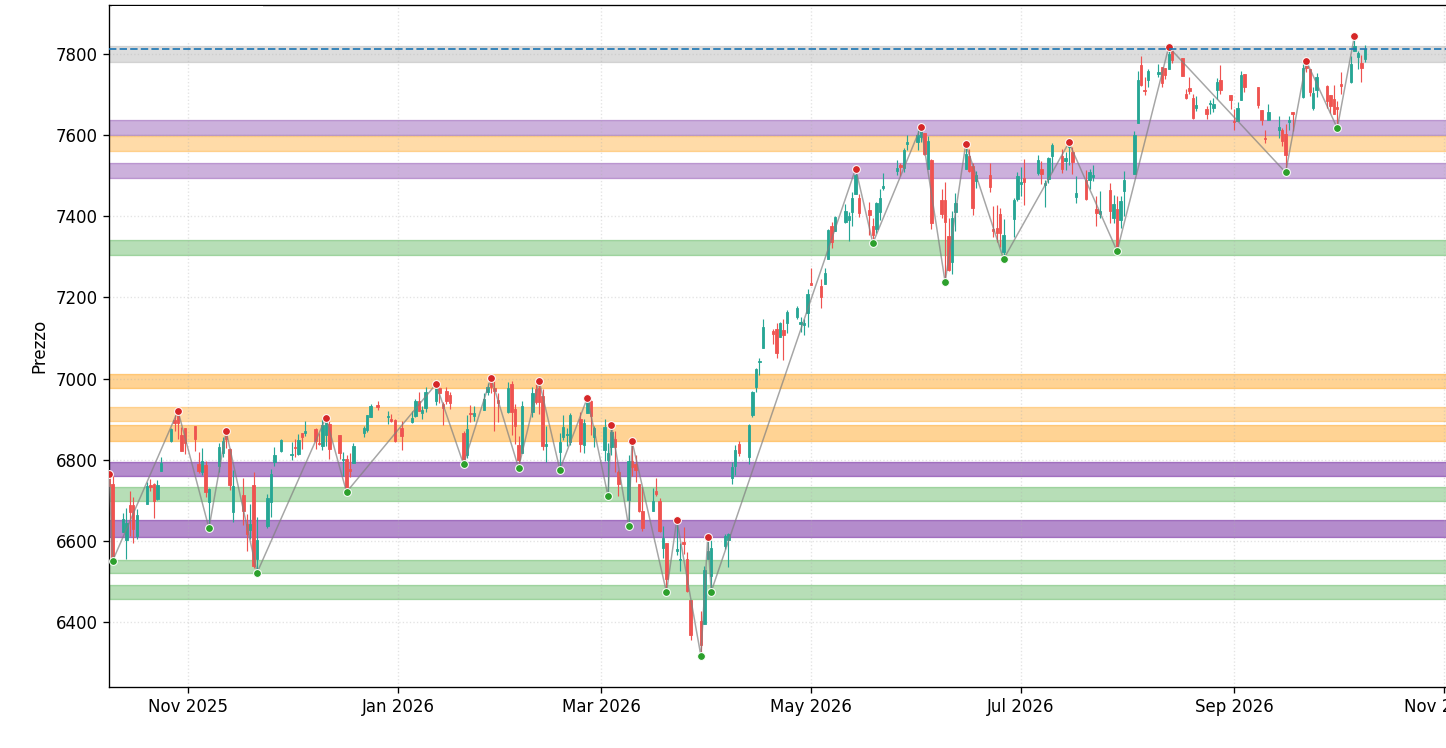
| S&P 500 ($SPX) | 7,811.54 | +0.59% | −0.09% from its 12-month closing high (7,818.93, October 6); +2.3% in a month; RSI 59.9; active long | 🟢 |
| Semiconductors ($SOX) | 12,572.42 | −0.41% | Above SMA50 (12,066.16); −14.1% from its 12-month closing high; active short | 🔴 |
| Financials ($XLF) | 54.73 | +0.92% | −4.1% in a month; below SMA50 (56.53), above SMA200 (53.69); RSI 45.6 | ⚪ |
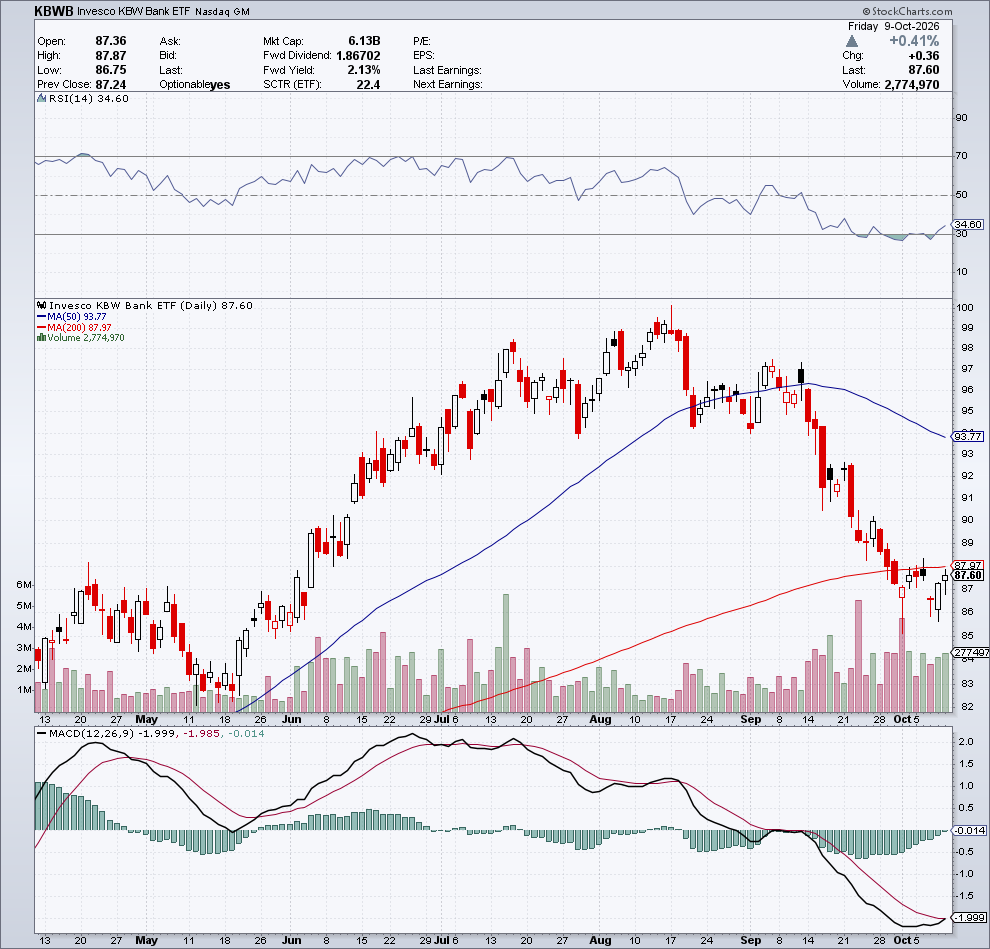
| Large banks ($KBWB) | 87.60 | +0.41% | −9.1% in a month; below SMA50 (93.77) and SMA200 (87.97); RSI 34.6 | 🔴 |
| Regional banks ($KRE) | 69.01 | −0.83% | −6.0% in a month; below SMA50 (73.70) and SMA200 (70.65); RSI 34.5 | 🔴 |
| US 10Y | 5.24% | +1.3 bps | +41 bps in a month (4.84% on September 9); below its 12-month closing high (5.31%, October 5); RSI 65.8 | 🔴 |
📊 Story in detail
🏢 1. Goldman goes overweight global equities on expected earnings growth of 25%, but the index has no cushion and the banks sit the first exam
What happened
Goldman Sachs’ strategy team, led by Christian Mueller-Glissmann, has raised its three-month view on global equities to ✅ overweight, from neutral, bringing it in line with its twelve-month view (Bloomberg, October 12). Rising oil prices and yields have stalled the rally and made valuations less stretched, while earnings remain solid: for the third quarter, the Bloomberg Intelligence consensus expects S&P 500 earnings to grow 📊 25% year over year, and Goldman expects more. The bank recommends a “barbell” strategy — global tech plus rate-sensitive, bond-like stocks whose valuations have come down since the summer — and names rates and energy as the main near-term risk.
The season opens ✅ Tuesday, October 13, with JPMorgan, Goldman Sachs, Wells Fargo and Citigroup, continues ✅ Wednesday, October 14, with Bank of America, Morgan Stanley and ASML, and ✅ Thursday, October 15, with TSMC. For the banks, analysts expect 📊 earnings down from the previous quarter, on lower trading and investment banking. Over the past month financials were the ✅ second-worst sector in the S&P 500, behind utilities, and the five big banks have lost ✅ about $270 billion in market value; according to Truist Securities, only ✅ 35% of institutional investors expect them to outperform the market, against 82% in December (Yahoo Finance). September CPI is due Wednesday, October 14: in August it ran at ✅ 3.4% year over year, and the consensus reported by Yahoo points to 📊 3.6%. The Fed raised rates on ✅ September 16 to 3.75–4% and meets again ✅ October 27–28.
What the sources say
“Earnings growth remains supportive for equities and the recent valuation de-rating has improved asymmetry into the third-quarter earnings season.” — Christian Mueller-Glissmann, Goldman Sachs (Bloomberg)
“We believe bonds should gradually move from portfolio headwind to hedge.” — Goldman Sachs’ team of strategists, on bond allocation (Bloomberg)
“…has been a little bit softer…” — David Solomon, CEO, Goldman Sachs, on fixed income, currencies and commodities trading in the third quarter (Barclays conference, September; Yahoo Finance)
“I think it’s safe to say 3Q is no 2Q.” — Daniel Simkowitz, co-president, Morgan Stanley (Barclays conference, September; Yahoo Finance)
FINBEAR Take: an upgrade with no cushion
Goldman talks about valuations coming down, but on the S&P 500 the price hasn’t given any ground: on Friday it closed less than a tenth of a percentage point from its high of the year, after gaining 2.3% in a month. If valuations have come down, it’s expected earnings that did the work, not the index. Buy on the upgrade and you’re buying near the highs, betting that reported earnings over the next few weeks deliver that expected 25% growth.
Then there’s the barbell, and this is where the week gets tight. The “bond-like” leg leans on rate-sensitive stocks, and their textbook example, utilities, was the worst sector in the S&P 500 over the past month, according to Yahoo Finance. Buying them means betting that yields, which climbed from 4.84% to 5.24% in a month, stop rising. As we read it, that leg is exposed to Wednesday’s CPI and to the Fed on October 28 — precisely the rate risk Goldman itself puts at the top of its list, alongside energy. The tech leg isn’t any more comfortable: semiconductors are more than 14% below their highest close of the year, the Pretore reads them as an active short, and on Thursday TSMC will show whether demand is holding. Both legs face their exams in the same week, and prices tell two different stories: utilities at the bottom of the month’s table, semiconductors up 5.4% over the same period but well off their high and still carrying an active short signal from the Pretore.
The first vote, though, goes to the banks — the sector that has moved opposite to the index over the past month. The large-bank ETF, $KBWB, has lost 9.1% and sits below its 50-day moving average and just below its 200-day; the regional-bank ETF is down 6.0%. Their own executives lowered the bar in September, and Goldman is among them: the bank whose CEO in September described fixed income, currencies and commodities trading as a little softer in the quarter is the same one now recommending stocks — the day before it reports those numbers.
Pretore vs the narrative. On the S&P 500 the Pretore’s signature is an active long, with the price 1.03% above the consensus AVWAP: for now, the chart sides with Goldman. But the closing-basis invalidation sits at 7,799.45, just 0.15% below Friday’s close. If the banks, inflation and TSMC pass their exams, the signature will have the numbers behind it too; a close below that level before the results arrive would instead say the market isn’t willing to wait for Goldman’s verdict. Tuesday and Wednesday the banks, Wednesday inflation, Thursday TSMC: three facts in a row, each able to confirm or dismantle Monday’s opinion.
Cui prodest?
Those who need the season to start well to keep the rally going into year-end — Bloomberg says so openly. And, as we read it, those selling equities: the upgrade lands the day before Goldman reports its own results, and the calendar puts the promise ahead of the numbers. Whoever waits until Wednesday evening will have more information, accepting that the price may move in the meantime.
For investors
| Item | Detail |
|---|---|
| Tickers involved | S&P 500 $SPX (ETF $SPY); banks $JPM, $GS, $WFC, $C, $BAC, $MS; financial ETFs $XLF, $KBWB, $KRE; the barbell’s tech leg $TSM, $ASML, semiconductors $SOX. Rates: US 10-year. Currencies, commodities and crypto not relevant to the story |
| Opportunities | If the banks and inflation pass the exam, Goldman’s thesis has the numbers on its side: an index at its highs backed by rising earnings estimates |
| Risks | Inflation above expectations with a Fed back to hiking; banks confirming the quarter-on-quarter drop in trading and investment banking; the 10-year at 5.24%; semiconductors carrying an active short signal; the Pretore’s S&P 500 invalidation 0.15% from the close |
| What to avoid | Buying Monday’s headline before Tuesday’s results; mistaking an upgrade for a discount: the index is a step away from its high of the year |
| Bottom line | The upgrade is an opinion; the facts arrive Tuesday, Wednesday and Thursday, in that order. Reading them in order costs two days; skipping them can cost the week. |
Impact: 🟢🟢 (2/5) — A constructive upgrade, but the test depends on this week’s banks and inflation
🔭 Scenarios and invalidation
Three main configurations, split by September CPI against the 3.6% consensus reported by Yahoo Finance. The S&P 500 and $KBWB levels are read on the same close, Friday, October 16; 87.97 is a fixed threshold — the value of $KBWB’s 200-day moving average on October 9. These are inferences from today’s data, not forecasts: price delivers the verdict.
▶▶▶ Central thesis — a partial pass. September inflation in line with consensus (3.6%) and banks with no surprises against the expected quarterly decline. The S&P 500 holds above 7,799.45 on a closing basis and the Pretore’s signature stands, but the banks don’t confirm: $KBWB stays below the 87.97 threshold on a closing basis, and the rally continues to rely more on expected earnings than on reported results.
▶▶ Alternative scenario — rates send the bill. Inflation above consensus: pressure would build for another Fed hike on October 28, the 10-year doesn’t retreat from 5.24% and the bond-like leg of Goldman’s barbell suffers. An S&P 500 close below 7,799.45 would invalidate the long signature; if it came by Wednesday, October 14, it would happen even before TSMC reports.
▶ Tail scenario — Goldman was right. Banks beat expectations and inflation comes in below the 3.6% consensus: yields fall, $KBWB closes back above the 87.97 threshold, and the S&P 500 closes above its high of the year (7,818.93). In that case the earnings promise is backed by results sooner than expected, and our caution needs revisiting.
📌 Thesis invalidation — This Flash’s thesis is caution on Goldman’s upgrade during exam week, with an S&P 500 that has no cushion above the Pretore’s threshold. It is invalidated if, with September inflation below 3.6%, at the close on Friday, October 16, the S&P 500 is above 7,818.93 and the large-bank ETF is above the 87.97 threshold. It’s a price test after the results, not proof that the banks beat expectations. Window: Friday, October 16 close. If triggered: FINBEAR’s caution gets scaled back, because prices will have confirmed the upgrade after the results, and the focus shifts to the Fed meeting on October 27–28.
🚨 Strategic Alerts
- S&P 500, the level of the week: the Pretore’s signature is an active long at 7,811.54; closing-basis invalidation at 7,799.45, 0.15% below, with the consensus AVWAP lower down at 7,731.63. A close below that level before the bank results and CPI would strip the upgrade of the chart’s support.
- Banks and inflation, Tuesday and Wednesday: results from JPMorgan, Goldman Sachs, Wells Fargo and Citigroup, then Bank of America and Morgan Stanley; on Wednesday at 2:30 p.m. Italian time, September CPI (expected at 3.6%, up from 3.4%, according to Yahoo Finance) and the Beige Book. The Treasury market is closed today for Columbus Day: rates cast their first vote tomorrow.
- Catalyst: TSMC on Thursday, October 15, for the barbell’s tech leg; Fed meeting on October 27–28.
📜 Disclaimer & Fantiborsa™ Maxim
🛡️ Disclaimer FINBEAR™: This Flash is editorial analysis, not investment advice. If an investment bank’s upgrade made you want to buy before you’d even read that same bank’s results, the problem isn’t in the report. We read the calendar; the order ticket is yours.
🎭 Fantiborsa Maxim™ of the day:
“On Monday Goldman upgrades stocks, on Tuesday it reports its own results: buy on the first and you’ve taken the chef’s word for the soup; wait for the second and at least you get a taste.”
© FINBEAR™ | Fantiborsa™ | Powered by Pythia™ — All rights reserved
📡 RADAR Flash™ FINBEAR — October 12, 2026
© FINBEAR™ | Fantiborsa™ | Powered by Pythia™ — All rights reserved